Visual Tools
Calculators
Tables
Mathematical Keyboard
Converters
Other Tools


Subspaces


Vector Spaces Inside Vector Spaces

A subspace is a subset of a vector space that is itself a vector space under the same operations. Lines and planes through the origin in R³, null spaces and column spaces of matrices, and solution sets of homogeneous systems are all subspaces. A simple two-condition test determines whether a given subset qualifies.


Definition

A subspace of a vector space VV is a nonempty subset W⊆VW \subseteq V that is itself a vector space when equipped with the same addition and scalar multiplication as VV.

Most of the ten axioms — commutativity, associativity, distributivity, the identity 1v=v1\mathbf{v} = \mathbf{v} — hold automatically in WW because they hold for all vectors in VV, and vectors in WW are vectors in VV. The properties that can fail are the closure conditions: the sum of two vectors in WW might land outside WW, or scaling a vector in WW might produce something not in WW. These are the only things that need checking.

Subspace Notation

Notation

Subspace Notation

The containment sign here is doing more work than it does in set theory — it is asked to carry a structural claim it cannot actually make on its own. Alongside it sit the two subspaces every space owns for free, and a circled plus that adds a uniqueness guarantee to an ordinary sum. All catalogued among the linear algebra symbols.
⊆\subseteq, ∩\cap, ∅\emptyset and set-builder braces come from set operation notation; 0\mathbf{0} and the bold-vector convention from vector notation; Col⁡\operatorname{Col}, Nul⁡\operatorname{Nul} and Row⁡\operatorname{Row} from fundamental-space notation; dim⁡\dim from dimension notation.
W⊆VW \subseteq V
W is contained in V — which is necessary for being a subspace, not sufficient
The same containment sign set theory uses, and it claims only membership: every element of WW lies in VV. Being a subspace is a strictly stronger condition that the symbol cannot express — closure under addition and scalar multiplication, which is what The Subspace Test below exists to check.
Also writtenW≤VW \le V in algebra texts, where the order symbol is borrowed precisely to say "substructure" rather than "subset" — the same convention that writes H≤GH \le G for subgroups. It is the honest notation for the claim, and this site does not use it.
Do not confuseReading ⊆\subseteq as though it already asserted subspacehood. The unit circle in R2\mathbb{R}^2 satisfies ⊆\subseteq and fails every closure test; the symbol is silent about structure, so the test has to be performed rather than read off.
{0}\{\mathbf{0}\} and VV
the zero subspace and the whole space
Every space owns exactly two subspaces for free, and both are called trivial — including VV itself. The braces matter: {0}\{\mathbf{0}\} is a set containing the zero vector, a space of dimension 00, while a bare 0\mathbf{0} is the vector itself.
Cases"Proper" excludes VV and nothing else, so a proper subspace may still be trivial in the other direction — {0}\{\mathbf{0}\} is proper. The two words cut the collection differently, which is why careful statements say "proper nonzero subspace" when they mean neither extreme.
Do not confuseThe empty set. ∅\emptyset is not a subspace of anything: a subspace must contain 0\mathbf{0}, so the smallest one is {0}\{\mathbf{0}\} — and this is the one place where a set-theory instinct gives the wrong smallest object.
W1⊕W2W_1 \oplus W_2
the direct sum of W-one and W-two
The circle is a promise. Ordinary W1+W2W_1 + W_2 collects every w1+w2\mathbf{w}_1 + \mathbf{w}_2; the circled version additionally asserts W1∩W2={0}W_1 \cap W_2 = \{\mathbf{0}\}, which makes each vector's decomposition unique — as Subspaces from Operations below states.
CasesWriting ⊕\oplus is therefore a claim, not a choice of typography: V=W1⊕W2V = W_1 \oplus W_2 says the pieces are independent as well as spanning, and it is what licenses dim⁡(W1)+dim⁡(W2)=dim⁡(V)\dim(W_1) + \dim(W_2) = \dim(V) with no correction term.
Same glyph elsewhereThe same circled plus means exclusive or in logic and addition modulo 2 in computing — unrelated jobs that happen to share the glyph, resolved entirely by what stands on either side of it.

The Subspace Test

A nonempty subset W⊆VW \subseteq V is a subspace if and only if it satisfies two closure conditions:

Subspace Test
W⊆V is a subspace  ⟺  {W≠∅u,v∈W⇒u+v∈Wv∈W, c∈F⇒cv∈WW \subseteq V \text{ is a subspace} \iff \begin{cases} W \neq \emptyset \\ \mathbf{u}, \mathbf{v} \in W \Rightarrow \mathbf{u} + \mathbf{v} \in W \\ \mathbf{v} \in W,\ c \in \mathbb{F} \Rightarrow c\mathbf{v} \in W \end{cases}
Learn more about this formula: Subspace Test →


Closure under addition: for all u,v∈W\mathbf{u}, \mathbf{v} \in W, the sum u+v\mathbf{u} + \mathbf{v} is in WW.

Closure under scalar multiplication: for all c∈Rc \in \mathbb{R} and all v∈W\mathbf{v} \in W, the product cvc\mathbf{v} is in WW.

These two conditions can be compressed into a single closure-under-linear-combinations condition:

Subspace Test Combined
W⊆V is a subspace  ⟺  W≠∅ and cu+dv∈W for all u,v∈W, c,d∈FW \subseteq V \text{ is a subspace} \iff W \neq \emptyset \text{ and } c\mathbf{u} + d\mathbf{v} \in W \text{ for all } \mathbf{u}, \mathbf{v} \in W,\ c, d \in \mathbb{F}
Learn more about this formula: Subspace Test Combined →


This single condition captures both closure properties simultaneously.

Pitfall: Stopping at the zero vector
Taking {(x,y):y=x2}\{(x, y) : y = x^2\} as a subspace because it contains (0,0)(0, 0) skips closure: 2⋅(1,1)=(2,2)2 \cdot (1, 1) = (2, 2) is not in the set, since 2≠222 \neq 2^2. Containing 0\mathbf{0} is necessary but not sufficient, and this set is not a subspace.

The requirement that WW be nonempty is essential. Once at least one vector v\mathbf{v} is known to lie in WW, closure under scalar multiplication with c=0c = 0 guarantees 0=0v∈W\mathbf{0} = 0\mathbf{v} \in W. So the zero vector belongs to every subspace. Conversely, if 0∉W\mathbf{0} \notin W, then WW cannot be a subspace — this is often the fastest way to disqualify a candidate.

A nonempty subset is a subspace exactly when combining its vectors never leads outside it; the other axioms come free from VV.

Trivial Subspaces

Every vector space VV has two subspaces that require no verification. The set {0}\{\mathbf{0}\} containing only the zero vector is a subspace: adding 0\mathbf{0} to itself gives 0\mathbf{0}, and scaling 0\mathbf{0} by any scalar gives 0\mathbf{0}, so both closure conditions hold. This is the smallest possible subspace, with dimension zero.

The entire space VV is also a subspace of itself — trivially, since every vector in VV is in VV and every operation on VV stays in VV. This is the largest possible subspace.

Every other subspace lies strictly between these two extremes: it contains 0\mathbf{0} but does not contain everything. Finding and classifying these intermediate subspaces is one of the central tasks of linear algebra.
R2×21001→{0}
A null space that is just {0}

An invertible matrix: reducing it leaves a pivot in every column and no free variable, so the only solution of Ax = 0 is x = 0. Its null space is the zero subspace {0} — the smallest subspace there is, and a subspace all the same. Compare it with a matrix whose null space is a line on the four fundamental subspaces visualizer.

The zero subspace appears naturally: it is the null space of every invertible matrix.

Subspaces of R² and R³

THEOREM
The subspaces of R2\mathbb{R}^2 are completely classified: {0}\{\mathbf{0}\}, lines through the origin, and R2\mathbb{R}^2 itself.

There is nothing else. Every line through the origin has the form {tv:t∈R}\{t\mathbf{v} : t \in \mathbb{R}\} for some nonzero vector v\mathbf{v}, and it is straightforward to verify that this set is closed under addition and scalar multiplication.

Fact: Lines through the eye look like points
To an eye at the origin, a whole line through the origin is seen end-on as a single point, and a plane through it as a single line. Projective geometry makes this a definition: the points of the projective plane are the lines through the origin of R3\mathbb{R}^3, and its lines are the planes through the origin.

The subspaces of R3\mathbb{R}^3 are: {0}\{\mathbf{0}\}, lines through the origin (dimension 11), planes through the origin (dimension 22), and R3\mathbb{R}^3 itself (dimension 33).

A line that does not pass through the origin — say the set {(1,0)+t(2,3):t∈R}\{(1, 0) + t(2, 3) : t \in \mathbb{R}\} — is not a subspace. It does not contain 0\mathbf{0}, and adding two vectors on this line produces a vector that is generally not on the line. Similarly, a plane that does not contain the origin fails the subspace test.

The geometric intuition is that subspaces are the "flat" subsets that pass through the origin. In Rn\mathbb{R}^n, every subspace is a span of some set of vectors, and its dimension equals the number of independent vectors needed to span it.
φabspan = ℝ²φabspan = line
The two non-trivial subspaces of R²

A plane through the origin above, a line through the origin below — in two dimensions these are the only shapes a subspace can take besides the origin itself and the whole space. Both pass through the origin, because a subspace must contain the zero vector, and both are closed: adding or scaling anything inside keeps you inside. Move the arrows and watch one become the other on the span and independence explorer.

Anything that misses the origin — a line offset from it, a shifted plane — fails the test before any closure question is asked.

The Null Space

For an m×nm \times n matrix AA, the null space is

The Null Space
Null(A)={x∈Rn:Ax=0}\text{Null}(A) = \{\mathbf{x} \in \mathbb{R}^n : A\mathbf{x} = \mathbf{0}\}

the set of all vectors that AA maps to the zero vector. This is a subspace of Rn\mathbb{R}^n.

Verification is direct. The zero vector satisfies A0=0A\mathbf{0} = \mathbf{0}, so 0∈Null(A)\mathbf{0} \in \text{Null}(A). If Au=0A\mathbf{u} = \mathbf{0} and Av=0A\mathbf{v} = \mathbf{0}, then A(u+v)=Au+Av=0+0=0A(\mathbf{u} + \mathbf{v}) = A\mathbf{u} + A\mathbf{v} = \mathbf{0} + \mathbf{0} = \mathbf{0}, so u+v∈Null(A)\mathbf{u} + \mathbf{v} \in \text{Null}(A). If Av=0A\mathbf{v} = \mathbf{0}, then A(cv)=cAv=c0=0A(c\mathbf{v}) = cA\mathbf{v} = c\mathbf{0} = \mathbf{0}, so cv∈Null(A)c\mathbf{v} \in \text{Null}(A). Both closure conditions hold.

The dimension of the null space is the nullity. By the rank-nullity theorem, rank(A)+nullity(A)=n\text{rank}(A) + \text{nullity}(A) = n. When AA has full column rank (rank=n\text{rank} = n), the null space is {0}\{\mathbf{0}\} and the map x↦Ax\mathbf{x} \mapsto A\mathbf{x} is injective. When the rank is less than nn, the null space is nontrivial and the map collapses some directions to zero.

Pitfall: Counting rows instead of columns
For A=(101011)A = \begin{pmatrix} 1 & 0 & 1 \\ 0 & 1 & 1 \end{pmatrix} of rank 22, using its 22 rows gives nullity 2−2=02 - 2 = 0, yet (−1,−1,1)(-1, -1, 1) solves Ax=0A\mathbf{x} = \mathbf{0}. With n=3n = 3 columns, the nullity is 3−2=13 - 2 = 1.

The count can be read off the reduced form of AA. Every column holds either a pivot or a free variable, the pivot columns number rank(A)\text{rank}(A), and each free variable contributes one vector to a basis of the null space. With nn columns in all, that leaves n−rank(A)n - \text{rank}(A) free variables.
R3×3120001000→A3×3121243364basis of N(A)3×12−10=03×1000
The null space read off the reduced form

Each free column has produced one special solution, and together they form a basis for everything the matrix sends to zero. The null space is a subspace for a reason visible right here: any combination of these solutions is still killed by the matrix, so the set is closed under exactly the two operations a subspace has to survive. Step through all four spaces on the four fundamental subspaces visualizer.

The column space in the next section is built the same way, from the pivot columns rather than the free ones.

The Column Space

For an m×nm \times n matrix AA with columns a1,…,an\mathbf{a}_1, \dots, \mathbf{a}_n, the column space is

The Column Space
Col(A)={Ax:x∈Rn}=Span{a1,a2,…,an}\text{Col}(A) = \{A\mathbf{x} : \mathbf{x} \in \mathbb{R}^n\} = \text{Span}\{\mathbf{a}_1, \mathbf{a}_2, \dots, \mathbf{a}_n\}

It is the set of all possible outputs of the linear transformation x↦Ax\mathbf{x} \mapsto A\mathbf{x}, and it lives in Rm\mathbb{R}^m.

The column space is a subspace because the span of any set of vectors is always a subspace. Its dimension equals the rank of AA.

THEOREM
The column space answers the solvability question: the system Ax=bA\mathbf{x} = \mathbf{b} has a solution if and only if b\mathbf{b} lies in Col(A)\text{Col}(A).

If b\mathbf{b} is a linear combination of the columns of AA, the coefficients in that combination are a solution vector x\mathbf{x}. If b\mathbf{b} is not in the column space, no solution exists.

To find a basis for the column space, row reduce AA and identify the pivot columns. The corresponding columns of the original matrix AA — not the echelon form — form a basis for Col(A)\text{Col}(A).
A3×3121243364→basis of C(A)3×2112334
Pivot columns as a basis for the column space

Row reduction marks the pivot columns; the matching columns of the original matrix, not of the echelon form, span every output Ax and form a basis for Col(A). Their number is the rank. Cycle through all four subspaces of this matrix on the four fundamental subspaces visualizer.

Ax = b is solvable exactly when b is a combination of these pivot columns.

The Row Space

The row space of an m×nm \times n matrix AA is the span of the rows of AA, viewed as vectors in Rn\mathbb{R}^n. Equivalently, it is the column space of ATA^T:

The Row Space
Row(A)=Col(AT)\text{Row}(A) = \text{Col}(A^T)

The row space lives in Rn\mathbb{R}^n and has dimension equal to the rank of AA — the same dimension as the column space, despite the two spaces living in different ambient spaces.

THEOREM
A key property is that elementary row operations do not change the row space.

Each row operation replaces rows with linear combinations of existing rows, so every row of the echelon form lies in the span of the original rows, and vice versa. The nonzero rows of the echelon form therefore provide a basis for the row space.

The row space and the null space together account for all of Rn\mathbb{R}^n. They are orthogonal complements: every vector in the null space is perpendicular to every row of AA (since Ax=0A\mathbf{x} = \mathbf{0} means the dot product of x\mathbf{x} with each row is zero), and their dimensions add up to nn.
Aspect Null space Null(A) Column space Col(A) Row space Row(A)
Definition { x : Ax = 0 } { Ax : x ∈ ℝⁿ } = Span of columns Span of rows = Col(Aᵀ)
Lives in ℝⁿ ℝᵐ ℝⁿ
Dimension nullity = n − r rank r rank r (same as Col)
Reader question it answers what inputs does A annihilate? (information lost) is Ax = b solvable? (set of reachable outputs) what is the total reach of the rows? (also equals Col(A) dim)
Basis from row reduction parametric form of Ax = 0; one vector per free variable original columns of A at pivot positions (not RREF columns) nonzero rows of the echelon form
Orthogonal complement (in its ambient space) row space Row(A), in ℝⁿ left null space Null(Aᵀ), in ℝᵐ null space Null(A), in ℝⁿ

Subspaces from Operations

New subspaces can be built from existing ones through set-theoretic operations, though not all operations preserve the subspace property.

The intersection of two subspaces W1W_1 and W2W_2 is always a subspace. If u\mathbf{u} and v\mathbf{v} both lie in W1∩W2W_1 \cap W_2, then u+v\mathbf{u} + \mathbf{v} lies in W1W_1 (since W1W_1 is a subspace) and in W2W_2 (since W2W_2 is a subspace), so it lies in W1∩W2W_1 \cap W_2. The same argument works for scalar multiples. The intersection can be anything from {0}\{\mathbf{0}\} (if the two subspaces share only the zero vector) to one of the original subspaces (if one contains the other).

Fact: Finitely many subspaces never fill Rn\mathbb{R}^n
Not even a million proper subspaces cover Rn\mathbb{R}^n: each is a flat slice of zero volume, and finitely many zero volumes add up to zero. With scalars 00 and 11 and arithmetic mod 22 this fails, since that plane has only four points and its three lines through the origin cover them all.

The union of two subspaces is almost never a subspace. If u∈W1∖W2\mathbf{u} \in W_1 \setminus W_2 and v∈W2∖W1\mathbf{v} \in W_2 \setminus W_1, the sum u+v\mathbf{u} + \mathbf{v} typically lies in neither W1W_1 nor W2W_2, violating closure. The only exception is when one subspace contains the other.

The sum W1+W2={w1+w2:w1∈W1,w2∈W2}W_1 + W_2 = \{\mathbf{w}_1 + \mathbf{w}_2 : \mathbf{w}_1 \in W_1, \mathbf{w}_2 \in W_2\} is always a subspace — it is the smallest subspace containing both W1W_1 and W2W_2. Its dimension satisfies

Dimension Sum Formula
dim⁡(W1+W2)=dim⁡(W1)+dim⁡(W2)−dim⁡(W1∩W2)\dim(W_1 + W_2) = \dim(W_1) + \dim(W_2) - \dim(W_1 \cap W_2)
Learn more about this formula: Dimension Sum Formula →


Pitfall: Adding dimensions without the overlap
Adding the dimensions of the xyxy-plane and the xzxz-plane in R3\mathbb{R}^3 gives dim⁡(W1+W2)=2+2=4\dim(W_1 + W_2) = 2 + 2 = 4, more than dim⁡R3=3\dim \mathbb{R}^3 = 3. The planes share the xx-axis, so the sum has dimension 2+2−1=32 + 2 - 1 = 3.

The subtracted term accounts for overlap. A basis of W1∩W2W_1 \cap W_2 can be extended to a basis of W1W_1 and to a basis of W2W_2, so the directions shared by both subspaces are counted once in dim⁡(W1)\dim(W_1) and again in dim⁡(W2)\dim(W_2); subtracting dim⁡(W1∩W2)\dim(W_1 \cap W_2) counts them a single time.

When W1∩W2={0}W_1 \cap W_2 = \{\mathbf{0}\}, the sum is called a direct sum, written W1⊕W2W_1 \oplus W_2, and every vector in the sum has a unique decomposition as w1+w2\mathbf{w}_1 + \mathbf{w}_2.
Operation on W₁, W₂ ⊆ V Always a subspace? Reason / formula
Intersection W₁ ∩ W₂ ✓ closure inherits from both — anything in both stays in both under + and scaling
Union W₁ ∪ W₂ ✗ in general not: u ∈ W₁ ∖ W₂ and v ∈ W₂ ∖ W₁ give u + v in neither (exception: one is contained in the other)
Sum W₁ + W₂ = { w₁ + w₂ } ✓ smallest subspace containing both; dim(W₁ + W₂) = dim(W₁) + dim(W₂) − dim(W₁ ∩ W₂)
Direct sum W₁ ⊕ W₂ (when W₁ ∩ W₂ = {0}) ✓ special case of sum; every v ∈ W₁ ⊕ W₂ has a unique decomposition v = w₁ + w₂
DownloadPNG2×PDF
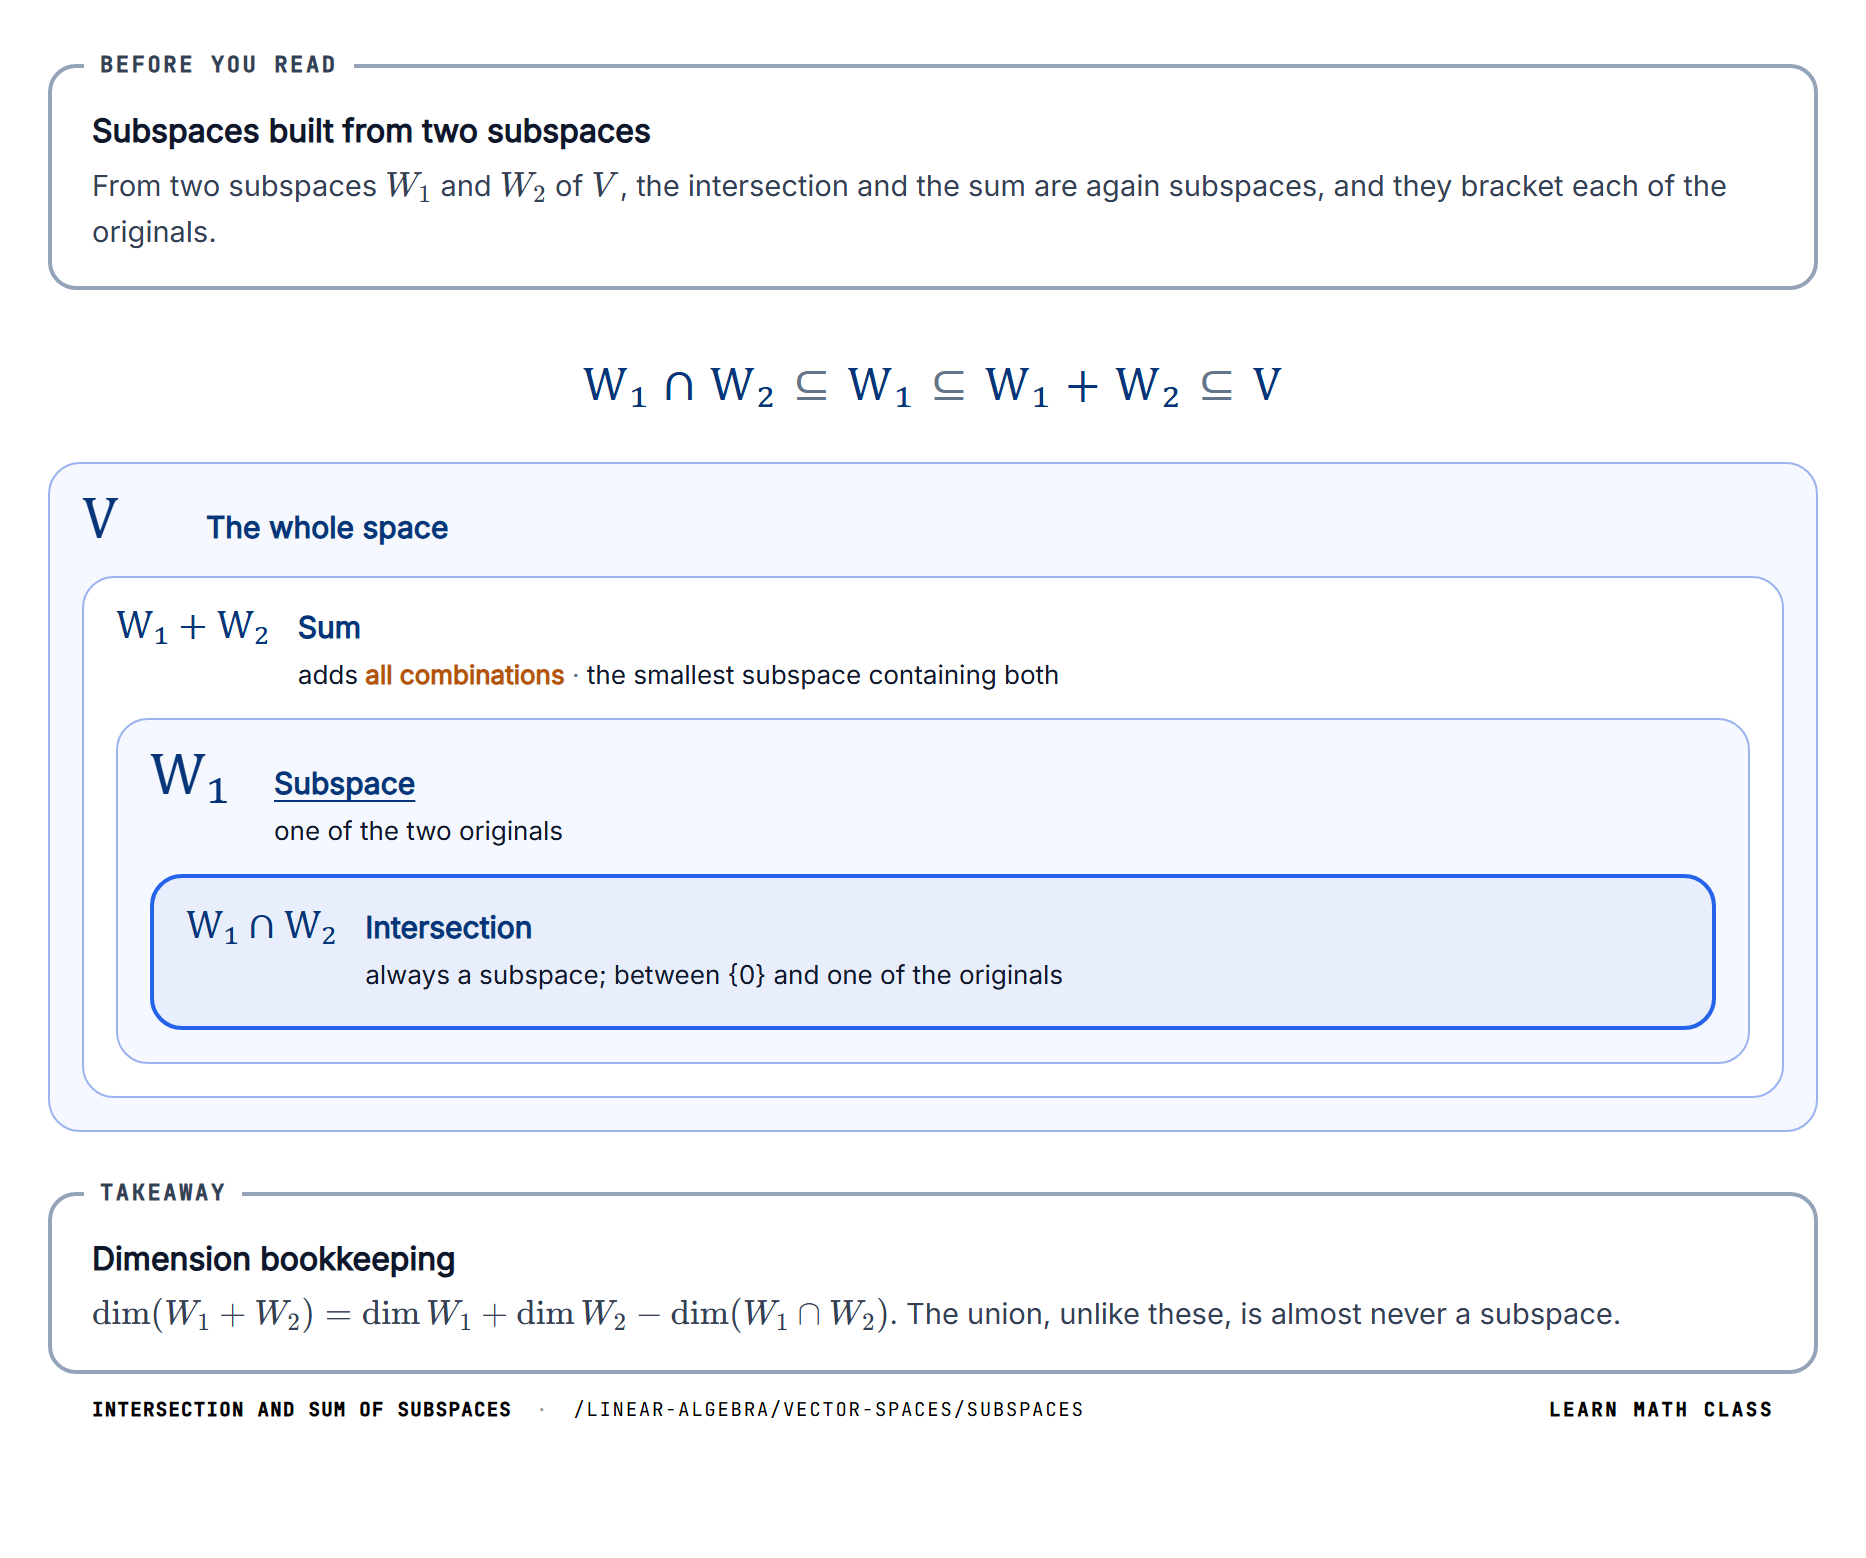
Before you read
Subspaces built from two subspaces
From two subspaces W1W_1 and W2W_2 of VV, the intersection and the sum are again subspaces, and they bracket each of the originals.

W₁ ∩ W₂⊆W₁⊆W₁ + W₂⊆V

V
The whole space
W₁ + W₂
Sum
adds all combinations · the smallest subspace containing both
W₁
one of the two originals
W₁ ∩ W₂
Intersection
always a subspace; between {0} and one of the originals
Takeaway
Dimension bookkeeping
dim⁡(W1+W2)=dim⁡W1+dim⁡W2−dim⁡(W1∩W2)\dim(W_1 + W_2) = \dim W_1 + \dim W_2 - \dim(W_1 \cap W_2). The union, unlike these, is almost never a subspace.
Intersection and sum of subspaces·/linear-algebra/vector-spaces/subspacesLearn Math Class
Intersections and sums of subspaces are always subspaces; a union almost never is, because closure breaks between the pieces.

Solution Sets and Subspaces

THEOREM
The solution set of a linear system Ax=bA\mathbf{x} = \mathbf{b} is a subspace only when b=0\mathbf{b} = \mathbf{0}.

In that case, the solution set is the null space of AA, which passes the subspace test as shown above.

When b≠0\mathbf{b} \neq \mathbf{0}, the solution set is not a subspace. It does not contain 0\mathbf{0} (since A0=0≠bA\mathbf{0} = \mathbf{0} \neq \mathbf{b}), and it is not closed under addition or scalar multiplication in general. However, the solution set has a clean geometric description in terms of subspaces.

If xp\mathbf{x}_p is any one particular solution to Ax=bA\mathbf{x} = \mathbf{b}, then every solution has the form

Solution Sets and Subspaces
x=xp+xh\mathbf{x} = \mathbf{x}_p + \mathbf{x}_h

where xh∈Null(A)\mathbf{x}_h \in \text{Null}(A) is a solution to the homogeneous system Ax=0A\mathbf{x} = \mathbf{0}. The full solution set is a translated copy of the null space — shifted away from the origin by the vector xp\mathbf{x}_p. In geometry, this is an affine subspace (also called a coset or a flat): a subspace that has been displaced from the origin.

This decomposition separates the particular and homogeneous contributions. The particular solution xp\mathbf{x}_p accounts for the right-hand side b\mathbf{b}, while the null-space component xh\mathbf{x}_h parametrizes the freedom in the solution. When the null space is trivial (Null(A)={0}\text{Null}(A) = \{\mathbf{0}\}), the solution is unique: x=xp\mathbf{x} = \mathbf{x}_p with no freedom.

Summary: Subspace Recognition

Every section of this page has answered a version of the same question — when is a given subset of a vector space a subspace? The two-condition test fixes the criterion, but in practice the answer follows almost mechanically from a small catalog of cases: the trivial subspaces; subspaces of ℝⁿ as flats through the origin; the matrix-derived null, column, and row spaces; affine sets that fail because they miss the origin; and asymmetric sets like the first quadrant that fail under negative scaling. The table below collects the recognition card across the candidates the page has discussed, with the verdict and a one-line reason.
A list of examples answers whether each one is a subspace. Sorting them by which clause of the test decides answers something more useful: what to check first, and what a near-miss looks like. The three groups below are the candidates that pass by definition, those that pass because linearity forces them to, and those that fail — with the failing clause named in each case.
Vector spaces · recognition

Subspace or not, and which clause decides

The test has three clauses — contains 0\mathbf{0}, closed under addition, closed under scaling — and a candidate fails by failing one of them. Sorting by which clause is what turns a list of examples into a diagnostic.

8candidates
Passes — by definition or trivially3
1
the largest subspace
V⊆VV \subseteq V
Closure holds because VV is a vector space to begin with. Worth stating so that "subspace" is understood as at most VV rather than strictly smaller — proper subspaces are the special case, not the definition.
2
dim⁡=0\dim = 0; the smallest
{0}\{\mathbf{0}\}
All three clauses hold directly: 0+0=0\mathbf{0} + \mathbf{0} = \mathbf{0} and c0=0c\mathbf{0} = \mathbf{0}. Its dimension is zero, not one — the empty set is its basis, since 0\mathbf{0} is dependent on its own and cannot belong to one.
3
automatically a subspace
Span⁡{v1,…,vk}\operatorname{Span}\{\mathbf{v}_1, \ldots, \mathbf{v}_k\}
A combination of combinations is a combination, so closure is immediate. This is the cheapest way to prove something is a subspace — exhibit it as a span and the test is already passed. Lines and planes through the origin are the k=1k = 1 and k=2k = 2 cases.
Passes — because linearity forces it2
4
subspace of Rn\mathbb{R}^n
Null⁡(A)={x:Ax=0}\operatorname{Null}(A) = \{\mathbf{x} : A\mathbf{x} = \mathbf{0}\}
If Au=0A\mathbf{u} = \mathbf{0} and Av=0A\mathbf{v} = \mathbf{0} then A(cu+dv)=0A(c\mathbf{u} + d\mathbf{v}) = \mathbf{0} — one line, both closure clauses. The homogeneous right-hand side is what makes it work, which is exactly why Ax=bA\mathbf{x} = \mathbf{b} below fails.
5
spans of the columns and rows
Col⁡(A)\operatorname{Col}(A), Row⁡(A)\operatorname{Row}(A)
Both are spans, so they inherit the result above without further argument. Together with the null space and left null space these are the four fundamental subspaces.
Fails — and which clause3
6
fails clause 1 — no 0\mathbf{0}
{x0+tv}\{\mathbf{x}_0 + t\mathbf{v}\}, x0∉Span⁡{v}\mathbf{x}_0 \notin \operatorname{Span}\{\mathbf{v}\}
Affine rather than linear. The origin test is the cheapest of the three and should be run first — it disqualifies this immediately, with no closure argument needed.
7
fails clause 1 — A0=0≠bA\mathbf{0} = \mathbf{0} \neq \mathbf{b}
xp+Null⁡(A)\mathbf{x}_p + \operatorname{Null}(A), b≠0\mathbf{b} \neq \mathbf{0}
The null space translated off the origin. Not a subspace, but a coset of one — which is why the general solution has the shape it does and why its dimension still comes from the null space.
8
{(x,y):x≥0, y≥0}\{(x, y) : x \geq 0,\, y \geq 0\}
Contains the origin and is closed under addition — two clauses out of three. Multiplying by −1-1 leaves the set, and that alone disqualifies it. The instructive case: passing most of the test is not passing it.
Note the near-misses are near in different ways. An affine set is closed under nothing that matters because it misses the origin; the first quadrant contains the origin and survives addition but not negative scaling. Both are the same distance from being a subspace and fail for unrelated reasons — which is why all three clauses have to be checked rather than the one that looks likeliest.
Subspace or not, and which clause decides·/linear-algebra/vector-spaces/subspacesLearn Math Class
In practice the origin test comes first because it is nearly free. Two of the three failures below are settled by it alone — an affine line and the solution set of Ax=bA\mathbf{x} = \mathbf{b} both miss 0\mathbf{0}, and neither needs a closure argument. Running the clauses in the order cheap-to-expensive means most non-subspaces are disqualified before any real work.
The first quadrant is the case worth dwelling on, because it passes two clauses out of three. It contains the origin, and the sum of two vectors with non-negative components has non-negative components — everything looks right until scaling by −1-1 leaves the set entirely. Passing most of the test is not passing it, and the clauses fail independently: nothing about closure under addition implies closure under scaling.
Common Pitfalls

Three mistakes come up again and again with subspaces. Each one is marked with a box where it happens in the sections above; here each is worked through in full, with the wrong and the right working side by side.

Stopping at the zero vector

A candidate set is checked for the zero vector, found to contain it, and declared a subspace without the two closure conditions being tested.

Wrong working: W={(x,y):y=x2}W = \{(x, y) : y = x^2\} contains (0,0)(0, 0), since 0=020 = 0^2, so WW is taken to be a subspace of R2\mathbb{R}^2.

Right working: test closure with vectors from WW. The point (1,1)(1, 1) is in WW, but 2⋅(1,1)=(2,2)2 \cdot (1, 1) = (2, 2), and 2≠22=42 \neq 2^2 = 4, so (2,2)∉W(2, 2) \notin W. Addition fails as well: (1,1)(1, 1) and (−1,1)(-1, 1) are in WW, but (1,1)+(−1,1)=(0,2)(1, 1) + (-1, 1) = (0, 2), and 2≠022 \neq 0^2. WW is not a subspace.

Why it happens: the zero-vector check is the quickest test and often the one that settles the question, so it gets treated as the whole test. It works in one direction only: a set without 0\mathbf{0} is ruled out, but a set with 0\mathbf{0} still has to pass both closure conditions.

How to check: after the zero-vector check, try one sum and one multiple with a negative scalar, using vectors from the set. A single result outside WW settles the question; if none turns up, prove closure with general vectors and a general scalar.

Counting rows instead of columns

The rank-nullity theorem is applied with the number of rows mm in place of the number of columns nn, so the nullity comes out as m−rank(A)m - \text{rank}(A).

Wrong working: A=(101011)A = \begin{pmatrix} 1 & 0 & 1 \\ 0 & 1 & 1 \end{pmatrix} has rank 22 and 22 rows, so the nullity is taken as 2−2=02 - 2 = 0 and Null(A)\text{Null}(A) as {0}\{\mathbf{0}\}.

Right working: the null space lives in Rn\mathbb{R}^n, with n=3n = 3 the number of columns. AA is already in reduced form, with pivots in columns 11 and 22 and x3x_3 free. The equations x1+x3=0x_1 + x_3 = 0 and x2+x3=0x_2 + x_3 = 0 give x=x3(−1,−1,1)\mathbf{x} = x_3(-1, -1, 1), so Null(A)=Span{(−1,−1,1)}\text{Null}(A) = \text{Span}\{(-1, -1, 1)\} and the nullity is 3−2=13 - 2 = 1.

Why it happens: an m×nm \times n matrix has two sizes, and the rows are what one sees when writing out the equations, while the null space is a set of inputs, one entry per column.

How to check: count the free variables in the reduced form, one for each column without a pivot. Here column 33 has no pivot, so the nullity is 11. Multiplying back confirms it: A(−1,−1,1)=(−1+1,−1+1)=(0,0)A(-1, -1, 1) = (-1 + 1, -1 + 1) = (0, 0).

Adding dimensions without the overlap

The dimension of a sum of subspaces is taken as dim⁡(W1)+dim⁡(W2)\dim(W_1) + \dim(W_2), leaving out the correction for the intersection.

Wrong working: the xyxy-plane W1W_1 and the xzxz-plane W2W_2 in R3\mathbb{R}^3 both have dimension 22, so dim⁡(W1+W2)=2+2=4\dim(W_1 + W_2) = 2 + 2 = 4.

Right working: the two planes meet in the xx-axis, so dim⁡(W1∩W2)=1\dim(W_1 \cap W_2) = 1 and dim⁡(W1+W2)=2+2−1=3\dim(W_1 + W_2) = 2 + 2 - 1 = 3. The sum is all of R3\mathbb{R}^3: any (a,b,c)(a, b, c) equals (a,b,0)+(0,0,c)(a, b, 0) + (0, 0, c).

Why it happens: for a direct sum the dimensions do simply add, and that case is carried over to sums whose pieces overlap.

How to check: a subspace can never have a larger dimension than the space it lies in. A result of 44 inside R3\mathbb{R}^3 is impossible, so the overlap has been missed.

Subspaces FAQ

Is every subset of a vector space a subspace?

+
No, and the containment symbol is silent on the matter. The unit circle in R2\mathbb{R}^2 is a perfectly good subset and fails closure immediately, since adding two points on it usually lands off it — (1,0)+(0,1)=(1,1)(1, 0) + (0, 1) = (1, 1), at distance 2\sqrt{2} from the origin. Writing W⊆VW \subseteq V asserts membership only; subspacehood is a structural claim that has to be tested.Read more →

Is the empty set a subspace?

+
No. Every subspace must contain the zero vector, so the smallest possible subspace is {0}\{\mathbf{0}\} rather than ∅\emptyset. This is the one place where set-theoretic instinct points at the wrong smallest object, since in ordinary set theory the empty set sits below everything.Read more →

What does writing V=W1⊕W2V = W_1 \oplus W_2 claim?

+
More than that the pieces combine to give VV. The circled plus asserts independence as well as spanning: every vector decomposes in exactly one way, and the two subspaces meet only at 0\mathbf{0}. That extra content is what licenses adding dimensions directly, with no correction term for overlap.Read more →